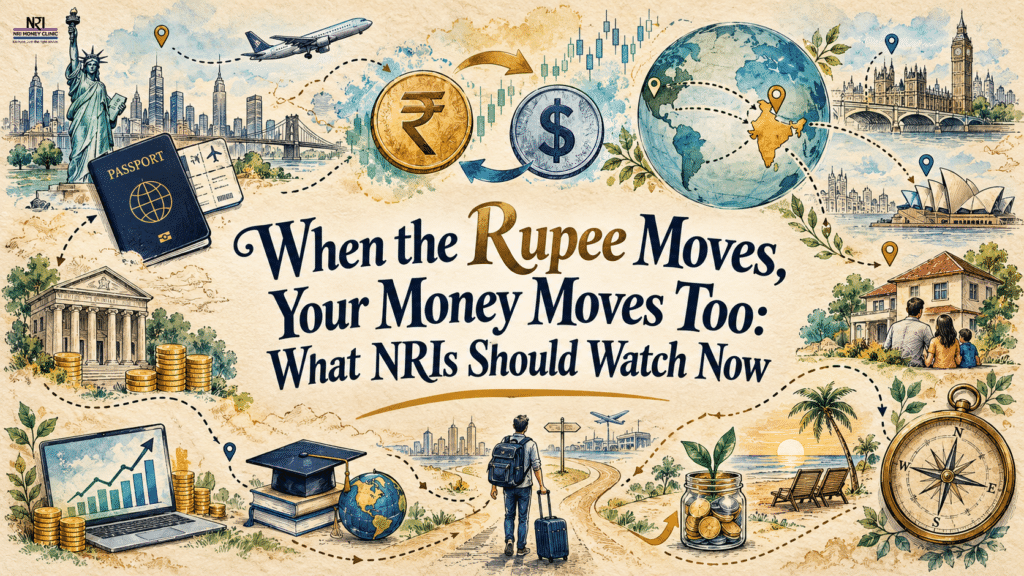
A dollar sent to India does not always buy the same number of rupees.
That sounds obvious.
But for an NRI who is investing in India, supporting family, paying an EMI, funding a property purchase or planning retirement back home, that small movement in the exchange rate can quietly change the value of an entire financial decision.
And right now, two phrases are appearing increasingly often in financial conversations:
Rupee liquidity and forex volatility.
They may sound like subjects meant for economists and currency traders.
They aren’t.
For an NRI, they can influence how much money reaches India, what an Indian investment is worth in another currency, how expensive overseas expenses become, and even how interest rates and fixed-income investments behave.
The important question, therefore, is not:
“Where will the rupee go next?”
It is:
“Is the financial plan prepared whichever way the rupee moves?”
First, what exactly is rupee liquidity?
Think of the banking system as a large reservoir.
Money flowing through banks is the water.
When there is plenty of rupee liquidity, banks have excess cash available in the financial system. When liquidity becomes tight, that surplus reduces and the cost of short-term money can increase.
The Reserve Bank of India constantly manages this reservoir.
And the current situation is particularly interesting because currency management and domestic liquidity have become closely connected.
Large foreign-currency inflows into India during 2026 added substantial dollar resources to the system. When foreign currency enters and is exchanged for rupees, more rupees can enter the domestic banking system.
But too much liquidity can create its own problems.
So the RBI has also been absorbing some of those excess rupees through foreign-exchange swaps, bond operations and other liquidity-management tools.
In late September, Reuters reported that the RBI’s recent foreign-exchange operations had drained roughly $20 billion in equivalent surplus rupee liquidity, after the banking-system surplus had risen sharply earlier in the month.
In simple language:
The RBI has been managing two taps at the same time: foreign currency on one side and rupees on the other.
For investors, that matters because liquidity conditions can influence short-term interest rates, bond yields and broader financial-market behaviour.
Then comes the second piece: the rupee itself.
The rupee entered October under renewed pressure.
On October 1, 2026, it fell to around ₹96.32 to the US dollar, its weakest level in about two months. Higher crude-oil prices, rising global bond yields and foreign portfolio outflows were among the pressures affecting the currency.
India imports a large portion of the energy it consumes.
So when crude becomes more expensive, India needs more dollars to pay for those imports. Greater dollar demand can put pressure on the rupee.
At the same time, higher US interest rates or bond yields can make dollar assets more attractive globally. Capital can move away from emerging markets, adding another layer of currency pressure.
That is why the rupee does not move simply because “India is doing well” or “India is doing badly.”
Currencies are relative.
The rupee can face pressure even when India’s domestic economy remains resilient because oil, global interest rates, capital flows, geopolitics and the strength of the US dollar are all moving simultaneously.
For NRIs, that distinction is important.
A weaker rupee can feel like good news. Until it isn’t.
Suppose an NRI sends $10,000 to India.
At ₹90 to the dollar, that becomes ₹9 lakh.
At ₹96, it becomes ₹9.6 lakh.
The same $10,000 suddenly delivers ₹60,000 more.
For an NRI sending money into India, a weaker rupee can therefore appear attractive.
But now reverse the transaction.
Suppose someone in India needs to fund overseas education, support a child abroad, travel internationally or move money towards a legitimate foreign-currency obligation.
The weaker rupee now works in the opposite direction.
More rupees are required to buy the same dollars.
That is why NRI Money Clinic believes currency movement should never automatically be labelled “good” or “bad”.
It depends on which direction the money needs to travel.
The bigger surprise comes when investment returns are calculated.
Imagine an NRI invests ₹1 crore in India.
A few years later, the portfolio becomes ₹1.15 crore.
On paper, that is a 15% gain in rupee terms.
But if the investor eventually needs that money in dollars, pounds, dirhams or another currency, the exchange rate at the time of conversion also matters.
A portfolio can perform well in rupees while delivering a very different return when measured in the investor’s home currency.
The reverse can also happen.
This leads to one of the most important ideas in NRI investing:
Investment return and currency return are not always the same return.
An NRI living in Dubai but planning to retire in India may reasonably want a substantial portion of future retirement assets linked to Indian expenses.
An NRI planning to fund a child’s US university education in three years has a very different requirement.
That future expense is in dollars.
The investment strategy should recognise that.
The goal should often determine the currency, not the latest forex headline.
Should NRIs wait for the “perfect exchange rate”?
This is where forex volatility can become psychologically expensive.
₹93 looks expensive when someone remembers ₹88.
Then ₹95 arrives.
The investor waits for ₹92.
The rupee touches ₹96.
Now the question becomes:
“Should the money be sent today, or should the family wait?”
The same behaviour happens in reverse when the rupee strengthens.
Trying to catch the perfect currency level can turn a long-term financial decision into short-term speculation.
For money that will be invested over many years, timing the entire transfer around one exchange-rate prediction may not make sense.
Large transfers can sometimes be staggered.
Near-term foreign-currency obligations can be planned earlier.
Education expenses can be mapped semester by semester.
Retirement money can be aligned with the country in which future expenses are expected.
The objective is not to predict every currency move.
It is to reduce the damage if the prediction is wrong.
October and November could remain important months
The coming weeks deserve attention because several forces are interacting at once.
Oil prices have been volatile. Global bond yields remain important for capital flows. The RBI has been actively managing excess domestic liquidity while intervening in currency markets to maintain orderly conditions.
At the same time, India’s substantial foreign-exchange reserves provide the central bank with room to manage periods of excessive volatility.
That does not mean the RBI will—or should—hold the rupee at one particular level.
The RBI’s long-standing approach has been to manage excessive volatility and disorderly market conditions rather than promise investors a particular exchange rate.
That difference matters.
An exchange rate can move even when the system is being actively managed.
For an NRI investor, therefore, the next few weeks may be better used for reviewing the financial plan than trying to forecast the next ₹1 move in USD/INR.
The NRI currency check-up
An NRI family can ask a few surprisingly powerful questions:
Where will the family ultimately spend this money?
Will retirement expenses be mainly in India or overseas?
Are children’s education costs likely to be in dollars, pounds or another currency?
Are Indian investments being evaluated only in rupee returns?
Is too much money being moved simply because today’s exchange rate “looks attractive”?
Are large transfers being timed emotionally?
And does the family have adequate liquidity in the currencies in which near-term expenses will actually occur?
The answers may reveal something important.
Sometimes, what looks like an investment problem is actually a currency-matching problem.
Don’t predict the rupee. Prepare for it.
There will always be a forecast saying the rupee will weaken.
Another will say it is undervalued.
Someone will predict a recovery.
Someone else will predict a new low.
But an NRI financial plan should not depend on one forecast being correct.
Rupee liquidity will change.
Interest rates will change.
Oil prices will change.
Capital will move across borders.
And currencies will continue to fluctuate.
That is not necessarily a reason to avoid investing.
It is a reason to invest with a clearer understanding of where the money will eventually be used.
For NRIs, wealth is rarely held in only one country or one currency. That complexity can feel like a disadvantage, but with thoughtful planning, it can also become diversification.
The goal is not to eliminate currency movement.
The goal is to make sure one currency movement does not derail an important life goal.
Is an NRI portfolio prepared for the next currency move?
NRI Money Clinic helps NRI families look at Indian investments, global assets, retirement, cash flow and cross-border financial goals as parts of one connected financial plan.
Wondering whether current rupee movements should change an investment or remittance decision? Click the WhatsApp link and message us to start the conversation.
The rupee will keep moving.
A well-planned financial future does not have to move with every headline.

No comment yet, add your voice below!