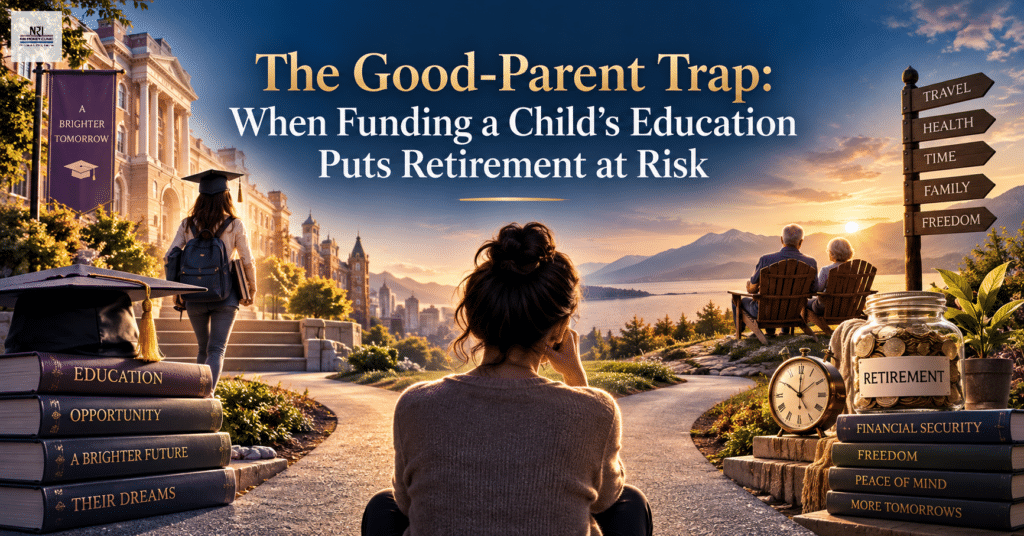
“Let the child get into the best university. The money can be managed somehow.”
For many parents, especially Indian parents, that sentence feels perfectly natural. Children come first. Their education comes first. Their opportunities come first. And retirement? That can wait.
But there is one uncomfortable question every parent needs to consider:
What if putting the child first today makes the child financially responsible for the parents tomorrow?
That is where something done out of love can quietly become a financial mistake.
The college acceptance letter that changes everything
For an NRI family, the conversation can become even more complicated.
A child may be considering universities in the US, UK, Canada, Australia, Europe, India or elsewhere. There is tuition, accommodation, insurance, travel, daily living expenses and possibly several years of postgraduate education.
Then there is currency. The family’s income may be in dollars or dirhams. Its investments may be partly in India and partly overseas. Retirement may be planned in India, while the child studies in another country altogether.
Suddenly, one education goal touches three countries, two currencies and a very large portion of the family’s savings. At this stage, parents can easily fall into the “whatever it takes” mindset.
Sell an investment? Fine.
Pause retirement contributions for a few years? Fine.
Dip into the retirement corpus? If necessary.
Take a large loan? We’ll manage.
The decisions may individually appear manageable. Together, they can change the family’s financial future.
Education and retirement are both important. But they are not identical goals.
This is where emotion and financial planning need to be separated. A child has several possible ways to fund higher education. There may be scholarships, grants, assistantships, education loans, part-time earnings where permitted, a more affordable university, a different country, or a combination of parental support and student borrowing.
The family also has the option of setting a budget. Retirement is different. There is no scholarship waiting at 65. There is no practical equivalent of an education loan designed to comfortably finance 20 or 30 years of retirement. And a retired couple cannot simply decide at 72 that they will work another 25 years to rebuild the corpus.
Education has alternatives. Retirement has far fewer second chances.
That is why sacrificing retirement completely to fund education can be a dangerous trade-off.
The biggest mistake isn’t spending on education
Parents spending generously on their children’s education is not the problem. The problem begins when the amount is determined by emotion rather than affordability. Consider two conversations.
The first goes like this:
“Choose the university you want. The family will somehow arrange the money.”
The second sounds different:
“The family has planned a certain amount for education. Now the family can evaluate universities, scholarships and funding options within that larger financial plan.”
Both parents want the best for their child. But only one family knows where the financial boundary lies. That boundary matters. Because a university should ideally be chosen not only on reputation, ranking or emotion, but also on return on investment, affordability and its impact on the family’s other financial goals.
The hidden cost of saying, “We’ll use the retirement money.”
Suppose parents withdraw ₹30 lakh from a long-term investment to bridge an education funding gap. It is tempting to think:
Education cost = ₹30 lakh.
But financially, that may not be the complete cost. The money also loses the opportunity to remain invested and compound. For illustration, ₹30 lakh growing at a hypothetical 10% annually for 15 years would become roughly ₹1.25 crore. That does not mean investors should expect or assume a 10% return. Investment returns are not guaranteed.
It simply demonstrates something important:
Money withdrawn from a long-term retirement portfolio loses time. And time is one of the hardest financial assets to replace.
An education loan may potentially be repaid over the early working years of a graduate’s career. Lost retirement compounding cannot be borrowed back later.
NRI parents have another complication: Which currency is the future in?
For NRI families, education planning and retirement planning should rarely be viewed in isolation. Consider a family earning in the UAE. The child’s education may be in the UK. The family’s major investments may be in India. And the parents may eventually retire in Bengaluru. There are four questions hidden inside what initially appears to be one simple goal.
How much will education cost?
Which currency will be needed?
Where should the education corpus be built?
And how much must remain untouched for retirement?
Currency movements can also affect the eventual education bill. A university fee quoted several years before admission may look affordable in today’s exchange rate. The actual rupee or other home currency cost may look very different when the payment finally becomes due.
That is why NRI education planning needs more than simply starting an investment labelled “Child Education”.
It needs a timeline, destination, currency strategy and funding target.
“But isn’t sacrificing for children what parents do?”
Yes. And perhaps that is exactly why this topic is difficult. Good financial planning is not asking parents to become less generous. It is asking them to redefine generosity. Imagine parents who spend almost their entire retirement savings on their child’s education. The child graduates without debt. Twenty years later, the parents do not have enough retirement income and become financially dependent on that same child. Was the child truly given financial freedom? Or was the liability simply postponed? Now consider another family.
The parents fund a large but affordable portion of education. The child receives a scholarship, selects a financially sensible university or takes manageable education financing for the remainder. Meanwhile, the parents protect their retirement plan. Years later, both generations are financially independent.
That too is good parenting.
Possibly an even more sustainable version of it.
The question isn’t “Child or Retirement?”
That is the wrong choice. A well-designed financial plan should not begin with:
“Whose future matters more?”
It should begin with:
“How can both futures be protected?”
That may mean deciding early how much the family can realistically contribute towards education. It may mean building a dedicated education corpus instead of treating the retirement portfolio as an emergency education fund. It may mean comparing universities based on total cost, not merely tuition. It may mean exploring scholarships rather than automatically assuming the parents must fund 100%. And sometimes, it may mean telling a child:
“This is what the family can comfortably afford. Now the decision can be made together.”
That conversation may initially feel uncomfortable. But financial clarity today can prevent financial resentment tomorrow.
A ₹1 crore education is not automatically better than a ₹50 lakh education
This is another assumption worth challenging. Expensive and valuable are not the same thing. When evaluating an overseas university, families can look beyond the brand name. What is the total cost of attendance? What opportunities does the programme realistically create?
Are scholarships available? How strong is the chosen field at that university? What alternatives deliver similar academic outcomes at a significantly lower cost? What happens if the child does not immediately find employment after graduation? And critically:
Can the parents pay for it without compromising retirement?
That last question deserves as much attention as university rankings.
Retirement is not “whatever is left”
Many families plan children’s education precisely.
The child is 10 years old.
College begins at 18.
Estimated cost: X.
Investment needed every month: Y.
Perfect. Then comes retirement planning.
“How much will retirement require?”
“We’ll see.”
That is backwards. Retirement should also have a number.
It should account for expected living expenses, inflation, healthcare, longevity, housing, travel and the lifestyle the family hopes to maintain. For NRI families, the calculation should also consider where retirement is likely to happen.
Someone retiring in India after spending decades abroad may have very different expenses from someone continuing to live in Singapore, Dubai, London, Toronto or the US. Until that retirement number is known, nobody truly knows how much of the portfolio is “available” for education.
Perhaps the greatest gift isn’t paying for everything
Parents naturally want to give their children a head start. But a completely debt-free education is not the only way to do that. Financial independence of the parents can itself be an extraordinary gift. It means the child can build a career without worrying about supporting parents prematurely. It means parents can make retirement decisions based on preference rather than financial necessity. It means both generations retain choices. And ultimately, isn’t that what wealth is supposed to create?
Choices.
Good parenting and good financial planning can coexist
Parents do not have to choose between a child’s dreams and their own retirement. The solution is planning early enough that the choice never becomes that extreme. Education can have its own corpus. Retirement can have its own corpus. Emergency reserves can remain emergency reserves.
Other investments do not have to be liquidated impulsively when the admission letter arrives. For NRI families, the plan can additionally account for currencies, countries, timelines, taxation, investment structures and the eventual place of retirement.
The goal is not:
“Spend less on the child.”
The goal is:
“Build a plan that protects the entire family.”
Because helping a child build an independent future is good parenting.
Making sure the child does not have to financially rescue the parents later is good parenting too.
Plan for both futures
A child’s education and the parents’ retirement are two of a family’s biggest financial goals. Neither should have to destroy the other.
NRI Money Clinic helps NRI families look at education, retirement, investments and cross-border financial goals as one connected plan.
Planning for a child’s higher education while wondering whether retirement savings are on track?
Click the WhatsApp link and message us to start the conversation.
A strong financial plan should allow parents to support their children’s dreams—and still have the freedom to enjoy their own future.

No comment yet, add your voice below!