You have a retirement plan. An investment portfolio. Maybe even a plan to buy that dream villa in India. But what about the one financial plan nobody likes talking about?
Your Will.
We know. Not exactly the most exciting topic to discuss over your morning coffee.
But here’s something worth thinking about.
You’ve spent years building your wealth, making investments, buying property, and securing your family’s future. Yet, have you decided what happens to all of it when you’re no longer around?
For Non-Resident Indians (NRIs), this question becomes particularly important. After all, when your life is spread across countries, your money often is too.
And leaving your family to figure out international inheritance laws, property documents, and multiple bank accounts isn’t exactly the legacy you had in mind.
Let’s talk about why making a Will deserves a place on your financial to-do list.
1. “I Don’t Have Crores. Why Would I Need a Will?”
Here’s a common misconception.
People often think Wills are for billionaires, business tycoons, and families fighting over ancestral mansions.
But you don’t need a sprawling estate or a dramatic family inheritance story to make a Will.
Have an apartment in India? Some mutual fund investments? Money in NRE or NRO accounts? Insurance policies? Jewellery?
Congratulations! You have an estate.
And that estate needs a plan.
A Will is simply a legal document that helps communicate who should receive your assets after your lifetime.
Without one, the distribution of your assets will generally be governed by the succession laws applicable to you.
And those laws may have very different ideas from yours.
The point isn’t how much you own. It’s making sure what you own reaches the people you intend it for.
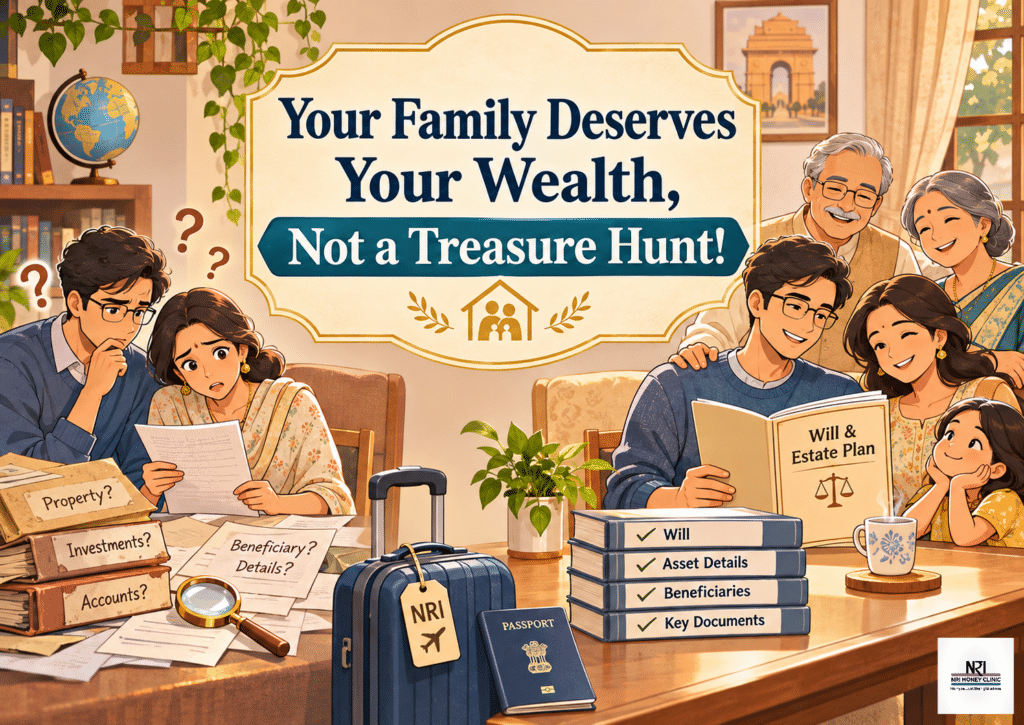
2. Your Family Should Inherit Your Wealth, Not a Treasure Hunt
Picture this.
An NRI has worked in Dubai for 25 years.
He owns a flat in Bengaluru, has mutual funds in India, savings in the UAE, and a few investments he made years ago.
Unfortunately, he passes away without leaving a Will.
His family now has a new full-time project.
Find the bank accounts. Locate the property documents. Identify the investments. Contact financial institutions. Establish legal heirship. Understand inheritance procedures in two countries.
And that’s before everyone starts asking, “Wait, who gets the apartment?”
What should have been a straightforward transfer of wealth could turn into months of paperwork, legal expenses, and confusion.
A Will cannot eliminate every legal formality, but a properly drafted one can make your intentions clearer and help reduce uncertainty.
Your family should be remembering you, not searching through old emails for a forgotten investment statement.
3. One Life. Two Countries. Multiple Sets of Rules.
Being an NRI comes with some wonderful advantages.
Global exposure. International career opportunities. Investments across markets.
But when it comes to estate planning, things can get complicated.
Imagine this financial arrangement:
- A house in Chennai.
- A bank account in Singapore.
- Investments in the United States.
- A spouse living in Dubai.
- Children studying in the United Kingdom.
That’s quite an international portfolio.
Unfortunately, inheritance laws don’t come with a universal instruction manual.
Different countries have different rules regarding succession, probate, taxation, and asset transfers.
So, does one Indian Will cover everything?
Maybe. Maybe not.
Depending on the countries involved, you may need separate Wills for assets in different jurisdictions.
But there’s a catch.
If those Wills aren’t carefully drafted and coordinated, one could unintentionally revoke or conflict with another.
Which means your estate plan needs to be as internationally coordinated as your financial life.
For NRIs, estate planning isn’t just about writing a Will. It’s about making sure that Will works wherever your assets are located.
4. “But I’ve Already Added a Nominee!”
This is probably one of the most common responses financial planners hear.
“I’ve added my wife as the nominee. Everything is sorted!”
Well, not necessarily.
A nomination and a Will are not always the same thing.
Depending on the asset and the applicable law, a nominee may be authorised to receive or deal with the asset after your death. But that doesn’t automatically mean the nominee becomes its ultimate legal owner.
The rights of legal heirs and beneficiaries may still need to be considered.
And the rules can differ between bank deposits, insurance policies, mutual funds, and other investments.
Think of it this way.
A nomination may help an asset move through the required process.
A Will helps establish your wishes about who should ultimately benefit from your estate.
A nominee is important. A Will is important. One doesn’t automatically replace the other.
So, if your entire estate plan begins and ends with “Nominee added successfully,” it may be time for a review.
5. No Will? The Law Has a Plan for You.
Here’s an interesting fact.
If you die without a valid Will, your estate doesn’t simply disappear.
Instead, the applicable succession laws generally determine how your assets are distributed.
This is called dying intestate.
Sounds complicated? It simply means you haven’t left a legally valid Will.
In India, succession rules can vary based on personal law, religion, the nature of the assets, and other circumstances.
The important thing to understand is that the legal distribution may not reflect your personal wishes.
Perhaps you wanted to leave a particular property to one child.
Maybe you wanted to provide additional financial support for a dependant.
Or perhaps you had specific plans for a family business.
Without proper estate planning, those intentions may not be carried out.
If you don’t make a plan for your estate, the law provides the default rules. And those rules may not be the ones you would have chosen.
6. “I’ll Make a Will When I’m Older.”
Ah, the classic financial planning promise.
Right up there with “I’ll start investing next month” and “I’ll review my insurance next year.”
The truth is, estate planning isn’t something you should think about only after retirement.
If you have assets, dependants, or specific wishes about how your wealth should be distributed, you have a reason to consider making a Will.
And life doesn’t exactly wait for your retirement party.
You might get married, have children, buy property, start a business, move abroad, or return to India.
Each of these milestones can change your financial responsibilities.
That’s why making a Will isn’t necessarily a one-time exercise.
Your Will should evolve as your life changes, with updates completed according to the applicable legal requirements.
The right time to think about your Will isn’t when you’ve finished living your life. It’s while you can still make the decisions yourself.
7. Making a Will: Less Complicated Than You Think?
A Will doesn’t necessarily have to be a hundred-page legal document filled with intimidating terminology.
But it does need to satisfy the applicable legal requirements.
For an ordinary unprivileged Will governed by the Indian Succession Act, this generally includes having the necessary legal capacity, signing the document appropriately, and obtaining attestation from at least two qualifying witnesses.
A well-prepared Will should also clearly identify your beneficiaries, describe the assets being distributed, and specify your intentions.
You’ll also want to appoint an executor.
Think of the executor as the person responsible for helping ensure your estate is administered according to your Will and the law.
Choose carefully. This is an important responsibility, not simply an honorary title.
Registration of an ordinary Will is generally not mandatory in India, although specific legal circumstances and requirements may differ.
For NRIs, professional guidance is particularly valuable because assets and beneficiaries may be located in different countries.
The objective is not to make the document complicated.
It’s to make your intentions clear, legally effective, and easier to implement.
8. What About Trusts? Are They Better Than Wills?
If you’ve been exploring estate planning, you’ve probably come across another term: family trusts.
So, should you create a trust instead of making a Will?
Not necessarily.
A trust can be useful when you want assets to be managed or distributed according to particular conditions.
For example, you may want to provide long-term financial support for a dependant, manage family business interests, or create a structured arrangement for significant assets.
But trusts also come with legal, administrative, and tax considerations.
They aren’t automatically better than Wills.
And you certainly don’t need a complicated structure simply because someone on the internet said wealthy families use trusts.
The right choice depends on your family circumstances, financial goals, and the countries involved.
Good estate planning isn’t about choosing the most sophisticated option. It’s about choosing the right one.
9. Your NRI Estate-Planning Checklist
Before you close this article and add “Make a Will” to that never-ending to-do list, here’s a practical starting point.
Step 1: Find out what you actually own.
Properties, bank accounts, mutual funds, insurance policies, business interests, and overseas investments. Make a proper inventory.
You might even rediscover an investment you’d completely forgotten about!
Step 2: Check your nominations.
Are your nominee details current? Do they align with your broader estate-planning intentions?
Step 3: Decide who should receive what.
Think about your beneficiaries and whether anyone requires special financial arrangements.
Step 4: Understand the rules across countries.
If you own assets in India and abroad, consult professionals who understand the relevant succession and tax laws.
Step 5: Make the Will and review it regularly.
A Will written ten years ago may not reflect your family or financial situation today.
Treat estate planning like a financial health check. Review it whenever life changes significantly.
10. The Most Important Financial Document You Keep Postponing
We spend an incredible amount of time thinking about money.
Which mutual fund should we invest in?
Should we buy property in India?
Is this the right time to convert dollars into rupees?
How much should we save for retirement?
All important questions.
But there’s another question that deserves just as much attention.
What happens to everything we’ve built when we’re no longer around?
A Will won’t make your investments grow faster.
It won’t improve your portfolio returns.
And it certainly won’t predict the stock market.
But it can help ensure that your wealth is passed on according to your wishes, within the framework of applicable law.
For NRIs, whose financial lives often span multiple countries, that clarity can be particularly valuable.
Because financial planning isn’t just about building wealth for yourself.
It’s also about making life easier for the people who matter most.
Your Wealth Has a Story. Make Sure It Has a Clear Next Chapter.
You worked hard for your money. You made sacrifices, took risks, invested patiently, and built something meaningful.
Now make sure there’s a plan for what comes next.
After all, leaving behind a legacy is wonderful. Leaving behind a financial puzzle? Not so much.
At NRI Money Clinic, we believe financial planning should look beyond investments and retirement to include the long-term financial well-being of your family.
Need help understanding how estate planning fits into your NRI financial journey?
Just message with your requirements on WhatsApp—we’ll help.
Disclaimer: This article is for educational purposes only and does not constitute legal, tax, or financial advice. Succession laws, will requirements, and cross-border inheritance rules vary by jurisdiction and individual circumstances. Consult qualified professionals before making estate-planning decisions.
No comment yet, add your voice below!